
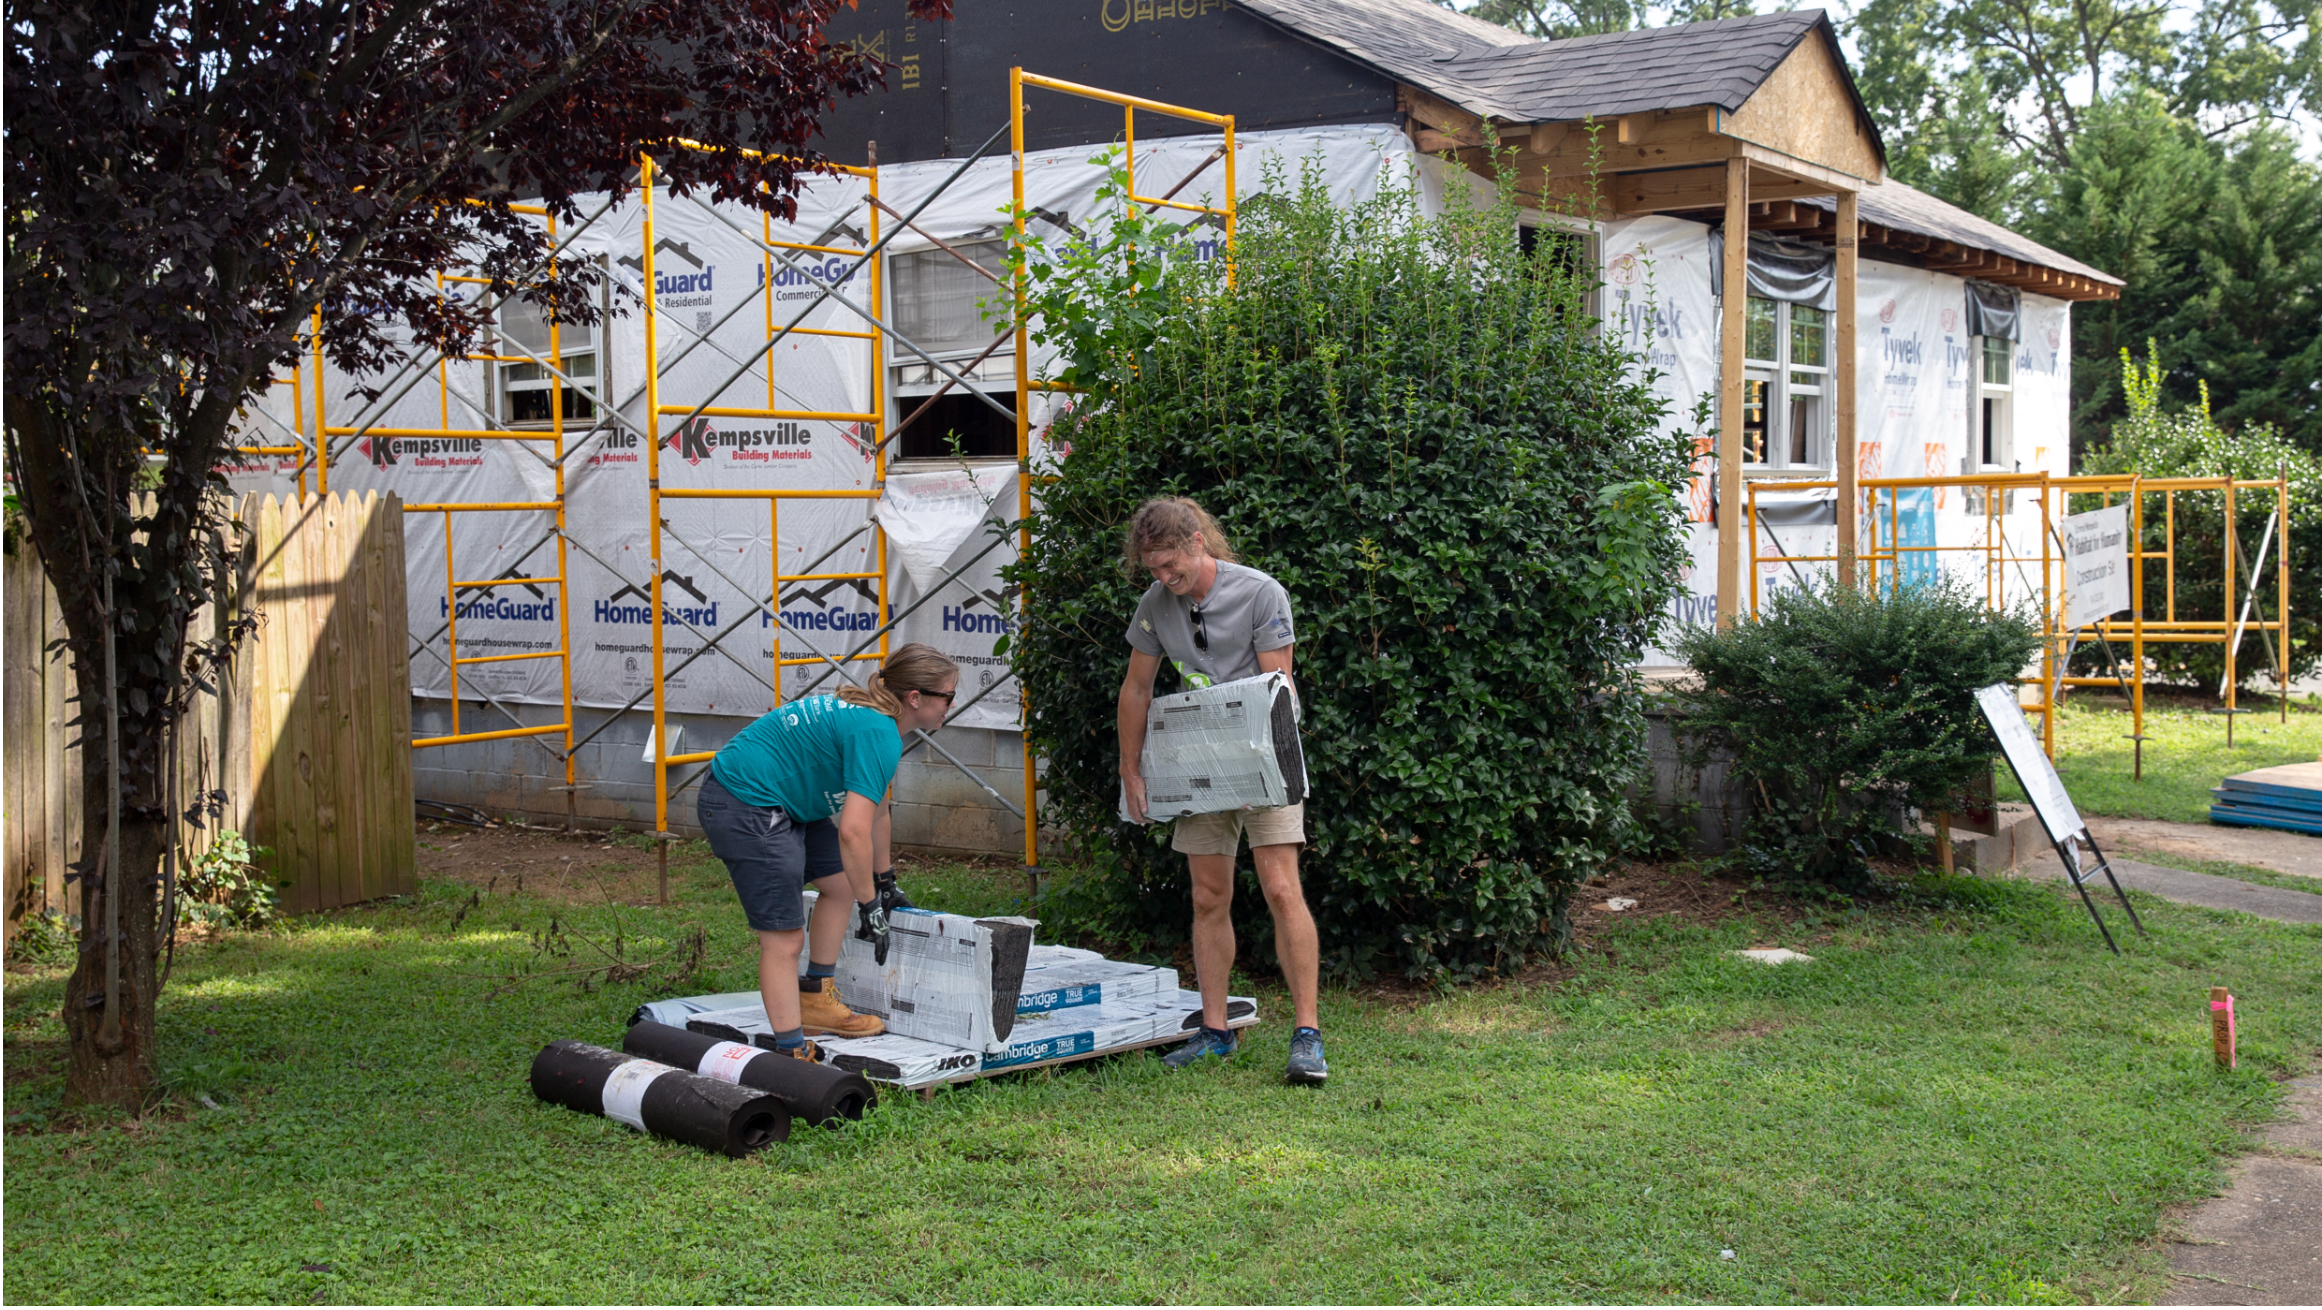
As homeownership becomes out of reach for more households, especially young first-time homebuyers, shared equity housing offers a promising path to homeownership. This model, in various forms, has been part of the American housing landscape for 150 years and helps families build wealth through homeownership while preserving affordability for future buyers.
The most common models include limited-equity housing cooperatives (LEHCs), community land trusts (CLTs), and deed-restricted homes sponsored by local governments, Habitat for Humanity affiliates, and other nonprofits. These established approaches help meet housing needs, but shared equity homeownership remains well short of its potential.
Understanding the origins of shared equity homeownership, how federal and state policies support these models, and barriers that still limit their growth can help policymakers expand access to this affordable homeownership option for future generations.
The history of shared equity homeownership models
Shared equity homeownership uses an initial public or mission-driven investment to make a home affordable and then limits future resale prices to preserve affordability for future generations. The model helps families who would likely remain renters build wealth while preserving the community’s investment. The three main types are the following:
- Limited-equity housing cooperatives: In LEHCs, residents buy shares in a cooperative that owns the building, with resale prices capped to maintain affordability for future buyers. The nation’s first cooperative was built in New York City in 1876, inspired by a movement in England that started a few decades earlier. From the beginning, cooperatives in New York tended to serve either the wealthy or immigrant workers, a dichotomy that still influences the trajectory of cooperatives. There are now at least 3,000 cooperatives with about 300,000 homes, about half of which are limited-equity cooperatives designed for long-term affordability.
- Community land trusts: In CLTs, homeowners own their homes, while the land is held in a community trust. A long-term ground lease limits resale prices to keep homes affordable. CLTs have their origins in the civil rights movement, with New Communities Inc. in Georgia establishing the first in 1969. Today, at least 340 CLTs steward more than 14,000 units nationwide, preserving and creating new housing and maintaining affordability and community cohesion.
- Deed-restricted homes: Deed restrictions are legal agreements that cap resale prices or limit who can buy homes to preserve affordability for a set period. Habitat for Humanity affiliates in the United States often use deed restrictions to create affordable homeownership opportunities. Unlike CLTs and cooperatives, deed restrictions generally do not include community governance.
Shared equity housing arose from various goals and circumstances. LEHCs were born to create homeownership opportunities in markets with high concentrations of multifamily buildings and prohibitive barriers to entry. Rooted in the civil rights movement, CLTs seek to democratize land ownership and governance. Deed-restricted homes, often developed through inclusionary housing programs, aim to economically integrate communities.
Shared equity programs also help buyers prepare for and sustain homeownership. Most offer prepurchase education and ongoing support, including assistance for owners facing financial difficulties. During the Great Recession, CLT homeowners experienced substantially lower rates of mortgage delinquency and foreclosure than homeowners overall.
These models expand homeownership for households priced out of the traditional market. Realizing their full potential, however, will require sustained investment and supportive policies.
New federal legislation expands support for shared equity housing
The 21st Century ROAD to Housing Act, enacted in July 2026, explicitly recognizes shared equity housing as a tool for preserving affordable homeownership. Its changes to the HOME Investment Partnerships program clarify support for CLTs, LEHCs, and other models that maintain long-term affordability.
The law also broadens HOME’s definition of a CLT. Rather than requiring the traditional CLT governance structure, the law allows qualifying nonprofits, states, and local governments to preserve affordability through ground leases, deed restrictions, or similar enforceable measures. This gives communities greater flexibility to design programs while retaining long-term affordability protections.
These changes could help more shared equity programs access HOME funding, but the law does not provide additional funding. Realizing its potential will require adequate resources and US Department of Housing and Urban Development guidance for state and local implementation.
The ROAD to Housing Act builds on earlier federal recognition of shared equity homeownership, though future mortgage market support remains uncertain. The Housing and Economic Recovery Act of 2008 established Fannie Mae and Freddie Mac’s Duty to Serve underserved mortgage markets, and the Federal Housing Finance Agency’s 2016 implementing rule explicitly recognized qualifying shared equity programs as an affordability preservation strategy. But the agency’s 2026 proposal would remove those explicit provisions for shared equity first mortgages, raising questions about future government-sponsored enterprise support.
States are also expanding support for shared equity housing
States are supporting long-lasting affordable housing through construction financing, partnerships with housing providers, and legal reforms that help shared equity programs develop more homes and connect them to eligible buyers.
In 2025, Colorado launched the Drive It Home program, which provides below-market construction financing to create affordable homeownership opportunities for low-income families. The homes must remain affordable for at least 20 years.
Meanwhile, Virginia Housing is investing directly in CLTs. In 2025, it allocated $4 million to five CLTs to support at least 40 new homes. Local providers such as Housing Alexandria also connect shared equity buyers with Virginia Housing’s homebuyer education and approved lenders to help eligible households become homeowners.
States are also addressing legal barriers to shared equity development. This year, Maryland enacted legislation establishing a clearer framework for forming and operating LEHCs. The law sets governance and resale requirements, authorizes grants to support their establishment, and limits certain local restrictions.
Turning policy into more affordable homes
Growing federal and state support creates an opportunity to expand shared equity homeownership, but turning that support into more affordable homes requires sustained investment and implementation.
The US Department of Housing and Urban Development and other federal agencies should provide clear guidance on new authorities, funding opportunities, and program requirements. State and local governments can incorporate shared equity into their housing grants, lending programs, and development strategies, adapting approaches from other communities to local markets and priorities.
Investment should support both housing development and ongoing stewardship, including the assistance and oversight that help homeowners remain financially stable and that preserve affordability for future buyers. Together, these efforts can expand homeownership opportunities while ensuring that today’s public investments continue to benefit future generations.
